Last updated on October 10th, 2026 at 11:55 am
For Americans frustrated by rising taxes, housing costs, insurance, and everyday expenses, moving abroad can look increasingly attractive. A growing number of countries actively compete for foreign residents through residency programs, favorable tax structures, retirement visas, and incentives designed to attract people with savings, pensions, remote income, or businesses. On paper, the numbers can look dramatically better than staying in the United States.
The appeal goes far beyond taxes. Many Americans looking overseas are also searching for cheaper housing, affordable healthcare, slower lifestyles, better public transportation, and the ability to live comfortably without earning an American-level salary. When lower taxes are combined with a lower cost of living, the difference in disposable income can become one of the strongest arguments for relocation.
But the phrase “low-tax country” can be dangerously misleading. A country may offer favorable treatment for certain foreign income while taxing local earnings heavily. Another may advertise attractive residency incentives but impose wealth taxes, social contributions, property taxes, or capital-gains rules that completely change the calculation. The headline rate rarely tells the whole story.
Americans also face an additional complication because moving abroad does not automatically end their relationship with the U.S. tax system. Depending on income, residency, tax treaties, credits, exclusions, and individual circumstances, Americans abroad may still have U.S. reporting obligations. That means the smartest relocation decisions are usually based on the combined tax picture rather than simply choosing the country with the lowest advertised rate.
Still, there are countries where the financial equation can genuinely work in an American expat’s favor. The key is understanding exactly who qualifies, which income receives favorable treatment, how long any incentive lasts, and what happens once temporary benefits expire. Lower taxes can be a powerful reason to move abroad, but only when the numbers survive a closer inspection.
Read here how to pack for Europe and Best eSIM for Europe
BOOK YOUR TRAVEL INSURANCE
Two of our favorite travel insurance: Heymondo Vs Safetwing cheapest travel Insurance. You can get for $135 USD your Heymondo Travel Insurance with Heymondo discount code valid for 90 days. Read our full comparison of Genki vs Safetywing Travel Insurance Review and the comparison Heymondo vs Genki
Quick & Easy Tips
Consult an international tax advisor before moving to ensure compliance with IRS expatriate rules and avoid double taxation.
Research long-term visa options and residency requirements in your chosen country to avoid fines or deportation risks.
Calculate total living costs, including rent, healthcare, food, and transport—not just tax savings—to assess realistic affordability.
The controversial truth is that countries offering attractive tax rules are not necessarily doing Americans a favor. They are competing for people with money. Retirees bring pensions and savings, remote workers bring foreign salaries, investors bring capital, and entrepreneurs can create businesses and employment. What looks like generosity is often a deliberate economic strategy.
This creates an uncomfortable contradiction. Governments may offer newcomers incentives that longtime residents never receive. A foreign retiree or highly paid remote worker can sometimes arrive with significantly more purchasing power than local residents while benefiting from rules created specifically to attract outsiders. Naturally, that can cause resentment, especially in places already struggling with housing affordability.
Americans can also fall into the trap of assuming that paying less tax automatically means having more money. That is not always true. If moving requires expensive private insurance, higher rents in expat neighborhoods, international accountants, legal fees, currency conversion, frequent flights home, or international schools, the supposed tax advantage can disappear surprisingly quickly.
There is also something ironic about moving overseas primarily to escape taxation while expecting excellent infrastructure, healthcare, transportation, public safety, and government services. Countries finance those systems somehow. A low personal tax bill does not necessarily mean the country itself is low-tax; it may simply mean your particular type of income receives favorable treatment.
The most controversial question is whether tax optimization should determine where somebody lives at all. Saving thousands annually sounds attractive, but choosing a country purely because of its tax rules can be a mistake if you dislike the language, climate, bureaucracy, culture, or distance from family. A tax strategy might look brilliant in a spreadsheet and miserable in real life.
United Arab Emirates (UAE)
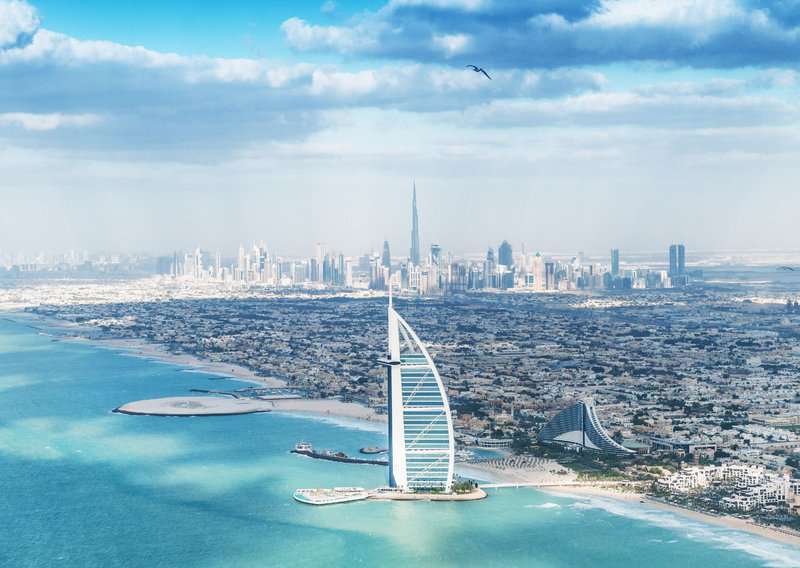
Why it’s tax‑friendly: No personal income tax, no capital gains tax or inheritance tax. Corporate tax is only 9% on profits over AED 375,000 (~$100,000).
Perfect for: High-earning professionals, entrepreneurs, digital nomads.
Residency options: Golden Visa for investors, freelancers, remote workers.
Hidden drawbacks: High cost of living in Dubai and Abu Dhabi; 5% VAT; no personal income streams like Social Security. It’s essential to ensure you’re not accidentally triggering U.S. taxation—so a cross-border CPA isn’t optional.
The Bahamas

Why it’s tax‑friendly: Zero personal income, capital gains, wealth, estate, or gift taxes.
Perfect for: Retirees, wealthy individuals seeking offshore living.
Residency options: Property-based permanent residency (~$1M investment) or annual residence permit .
Hidden drawbacks: Living costs are about 9% higher than the U.S. , limited infrastructure, and reliance on imports. Also, your U.S. tax obligations remain—but foreign exclusion can help.
Monaco
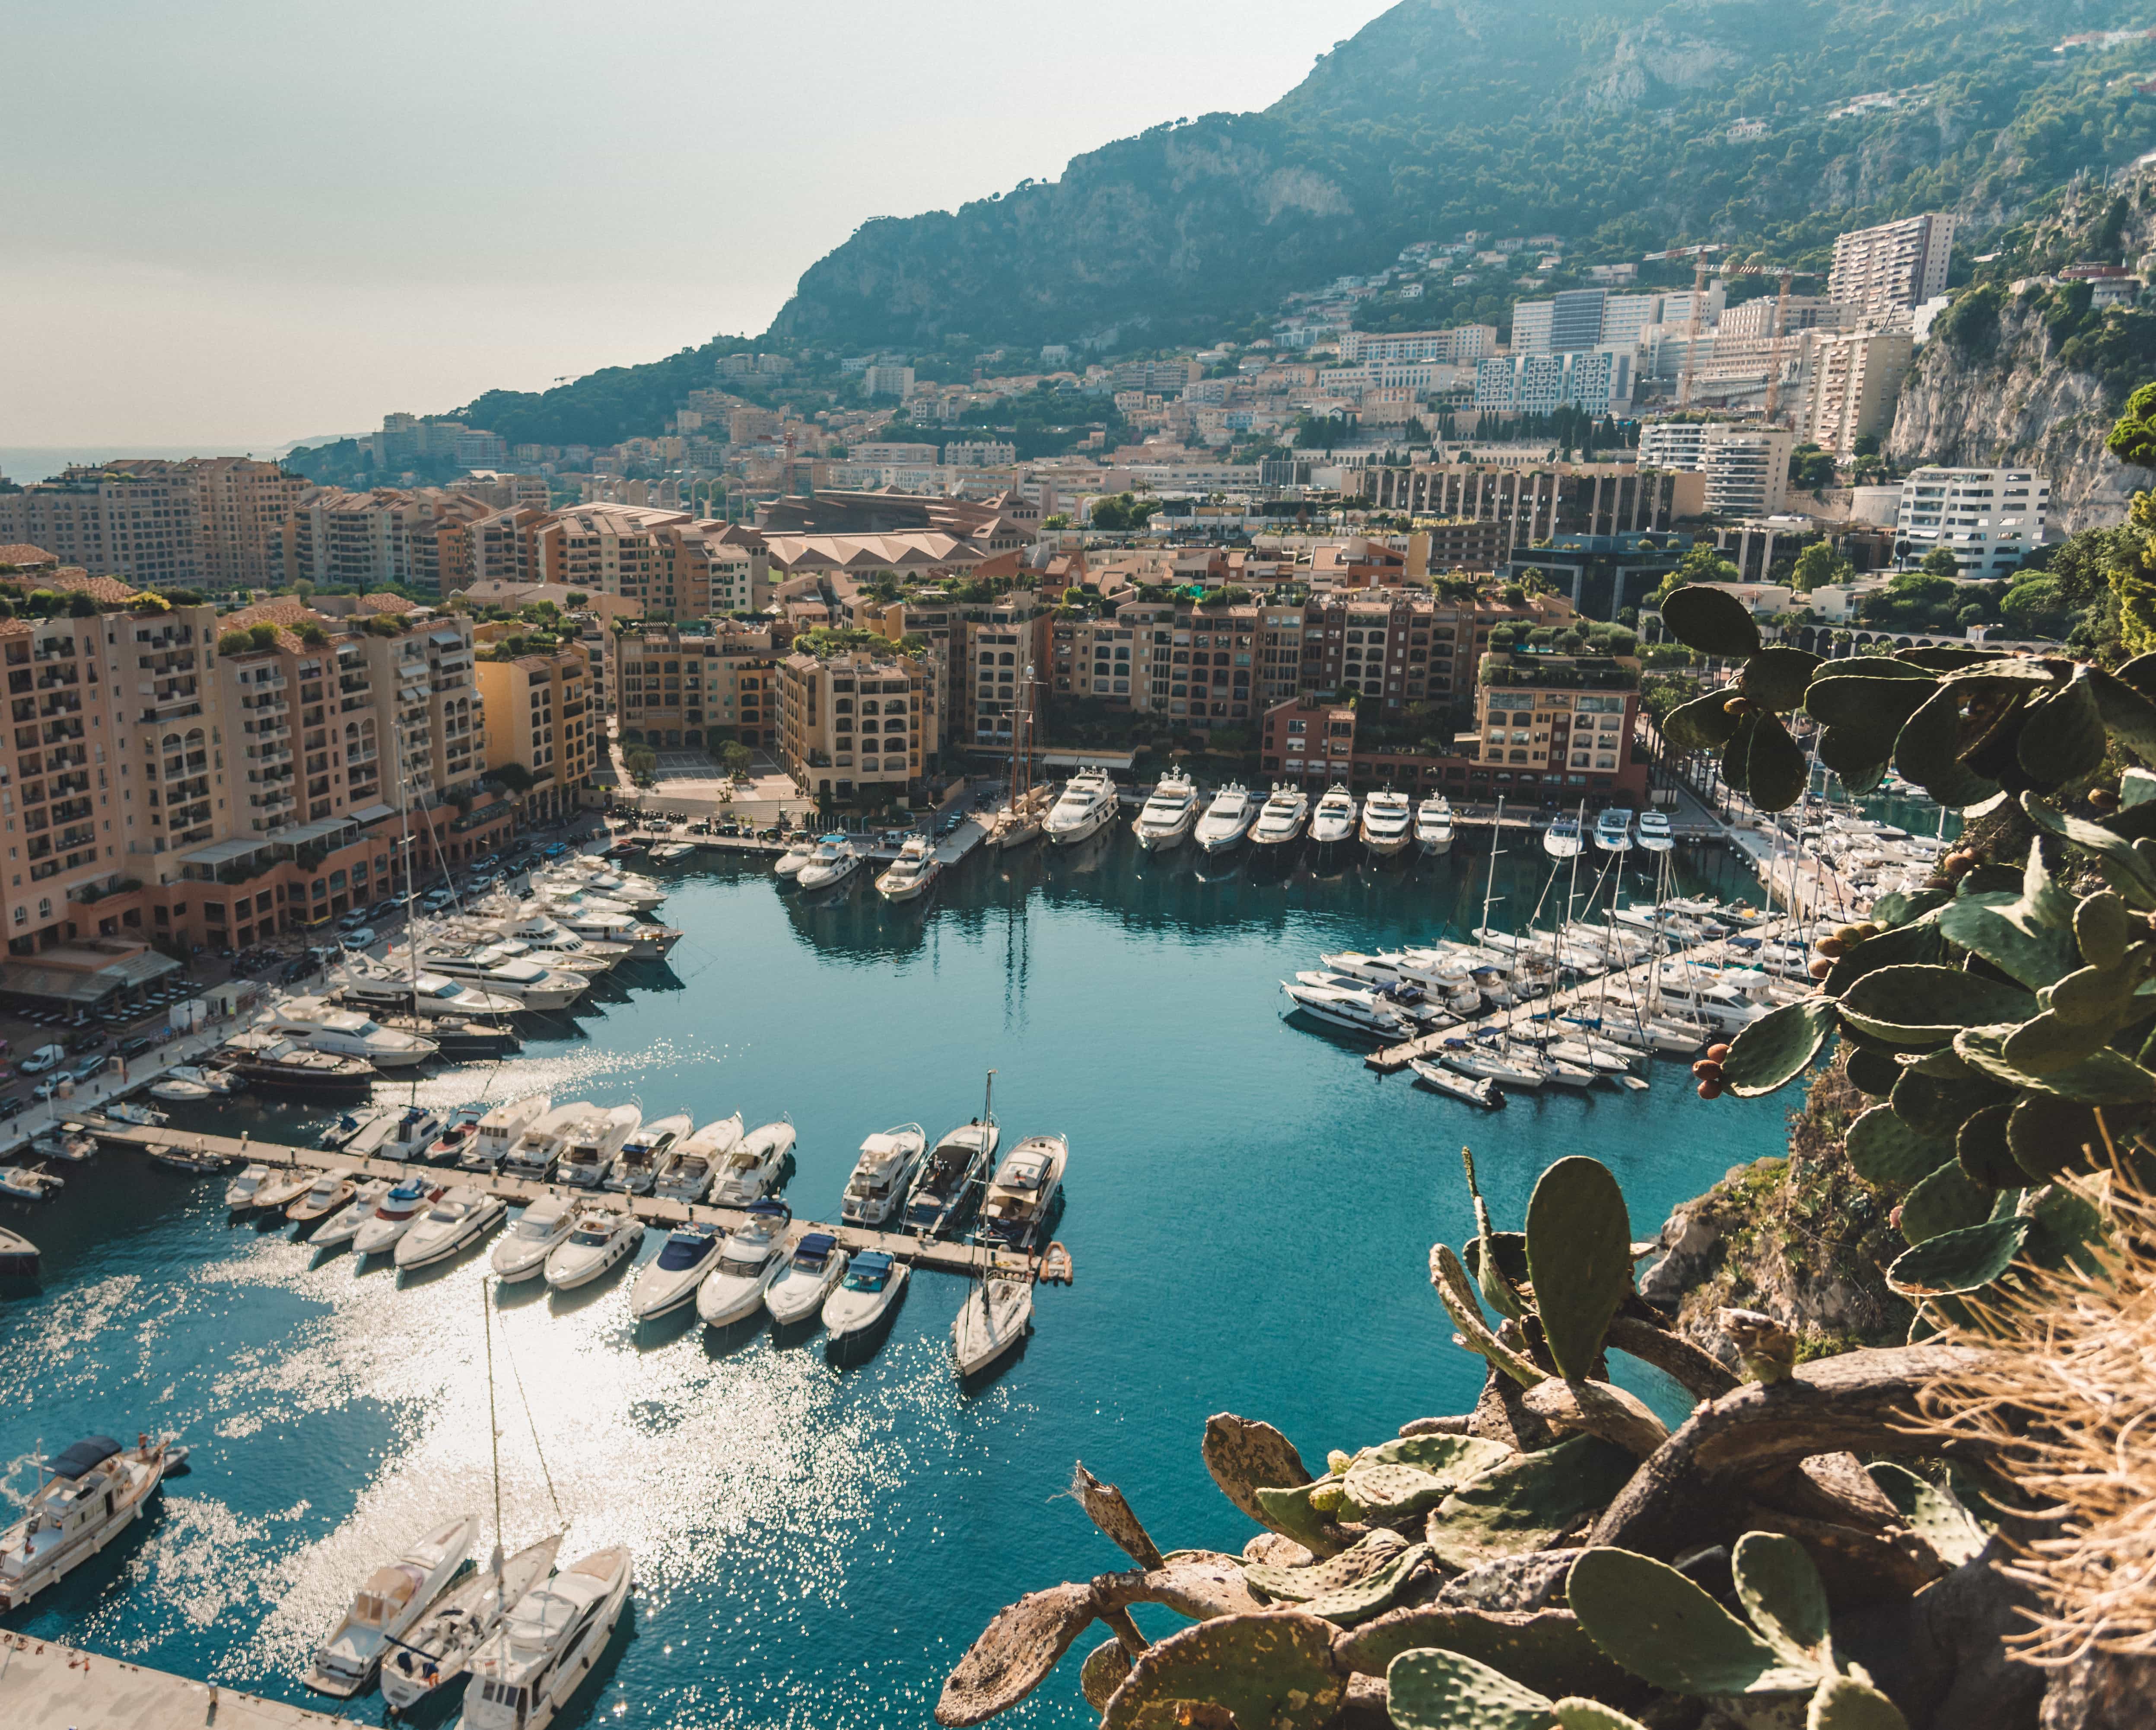
Why it’s tax‑friendly: No income tax (except French nationals), no wealth or capital gains tax.
Perfect for: Ultra‑high‑net‑worth individuals valuing privacy and prestige.
Residency requirements: ~€500,000 bank deposit, proof of accommodation, clean record .
Hidden drawbacks: Insane real estate (~€100K/m²) , 20% VAT, and 33% employer contributions. Feels more like a gilded cage than a financial liberty.
Panama
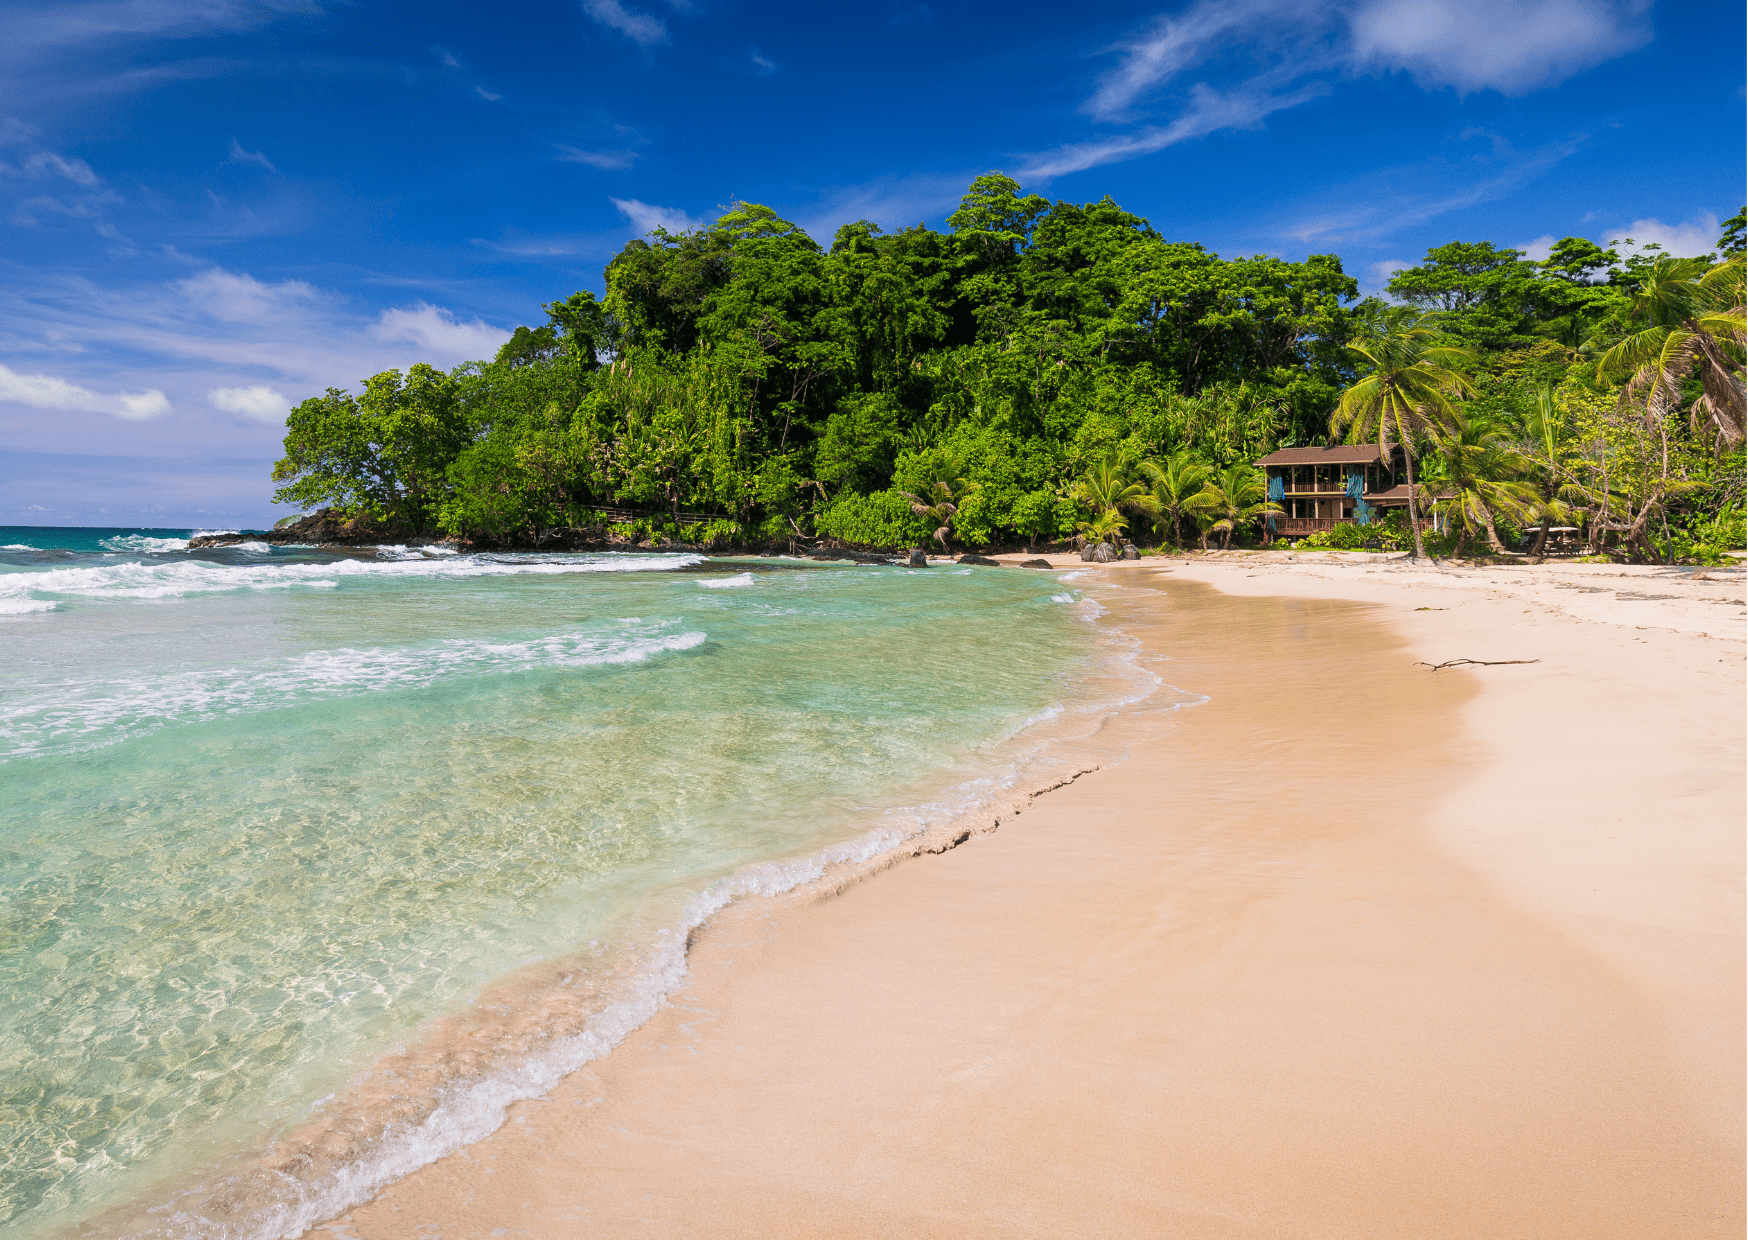
Why it’s tax‑friendly: Territorial tax model—no tax on foreign‑sourced income.
Perfect for: Retirees, remote workers, entrepreneurs.
Residency options: Pensionado (low income limit), Friendly Nations Visa.
Hidden drawbacks: Banking and infrastructure may lack Western reliability; past tax‑haven stigma is fading but can pose financial missteps.
Georgia

Why it’s tax‑friendly: 1% tax on small business income; no tax on undistributed profits; flat 20% personal tax is avoidable for freelancers.
Perfect for: Freelancers, micro‑business owners, digital nomads.
Residency perks: U.S. citizens can stay up to 1 year visa‑free.
Hidden drawbacks: Healthcare and infrastructure still developing; learning curve in bureaucracy, though simplified .
Bulgaria
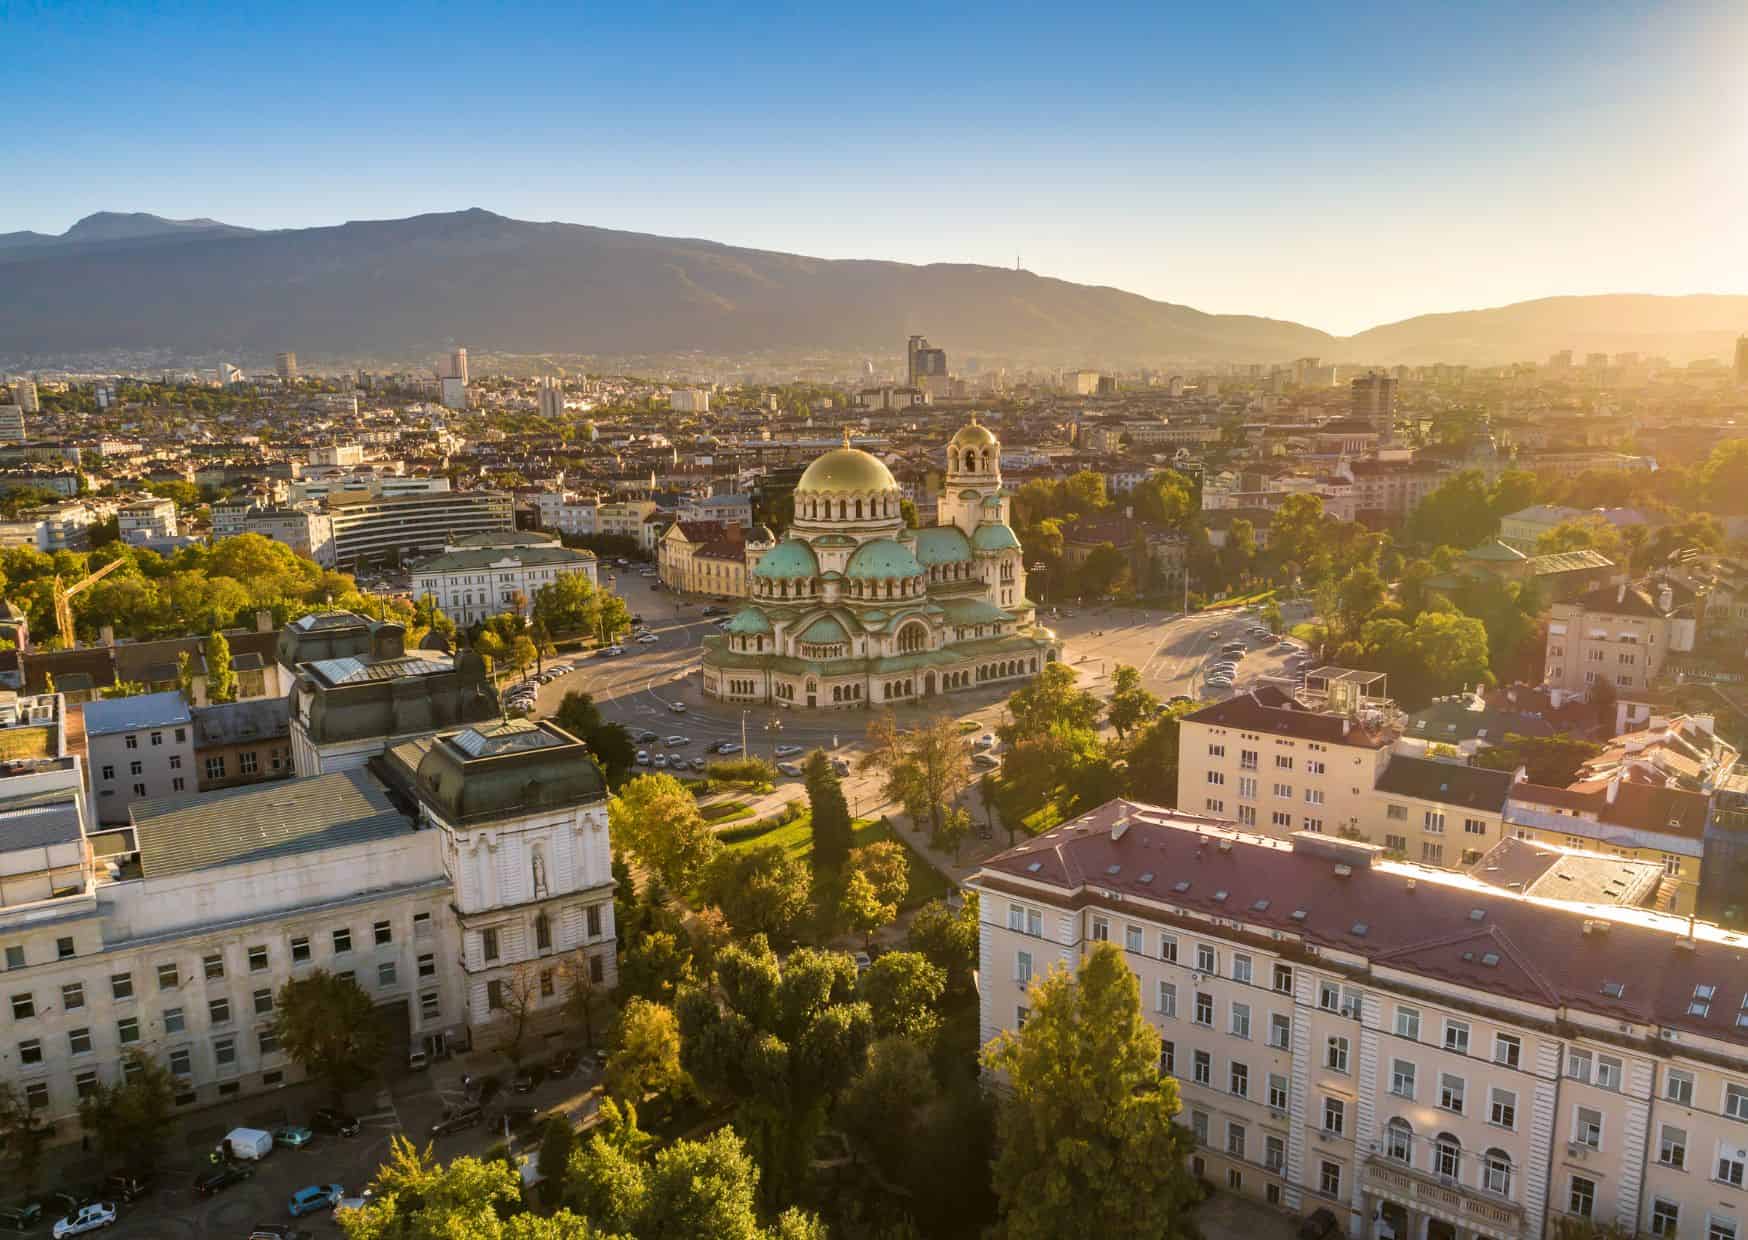
Why it’s tax‑friendly: Flat 10% on personal and corporate income; 5% dividend tax; no wealth tax.
Perfect for: Business owners, retirees, remote professionals.
Residency options: Invest, start a business, or apply for D visa.
Hidden drawbacks: Earnings potential lower; fewer expat services outside Sofia.
Malaysia

Why it’s tax‑friendly: No tax on foreign‑sourced income; under “My Second Home” (MM2H) visa.
Perfect for: Retirees, passive income earners.
Residency perks: 5–10 year visas with relaxed rules.
Hidden drawbacks: Not all foreign‑sourced income qualifies; must maintain visa investment; healthcare still good but varying.
Portugal

Why it’s tax‑friendly: Non‑Habitual Resident (NHR) program 10% flat on foreign pensions, no wealth or inheritance tax.
Perfect for: Retirees, remote workers, creative professionals.
Residency options: D7 visa, Golden Visa, digital nomad visa.
Hidden drawbacks: Soaring real estate prices and gentrification ; bureaucratic paperwork delays.
Costa Rica

Why it’s tax‑friendly: Territorial tax (no foreign income tax); pensionado visa for retirees.
Perfect for: Retirees, eco‑minded residents.
Residency options: Pensionado (income min), digital nomad visa.
Hidden drawbacks: Income threshold prejudices; inconsistent public healthcare.
Thailand
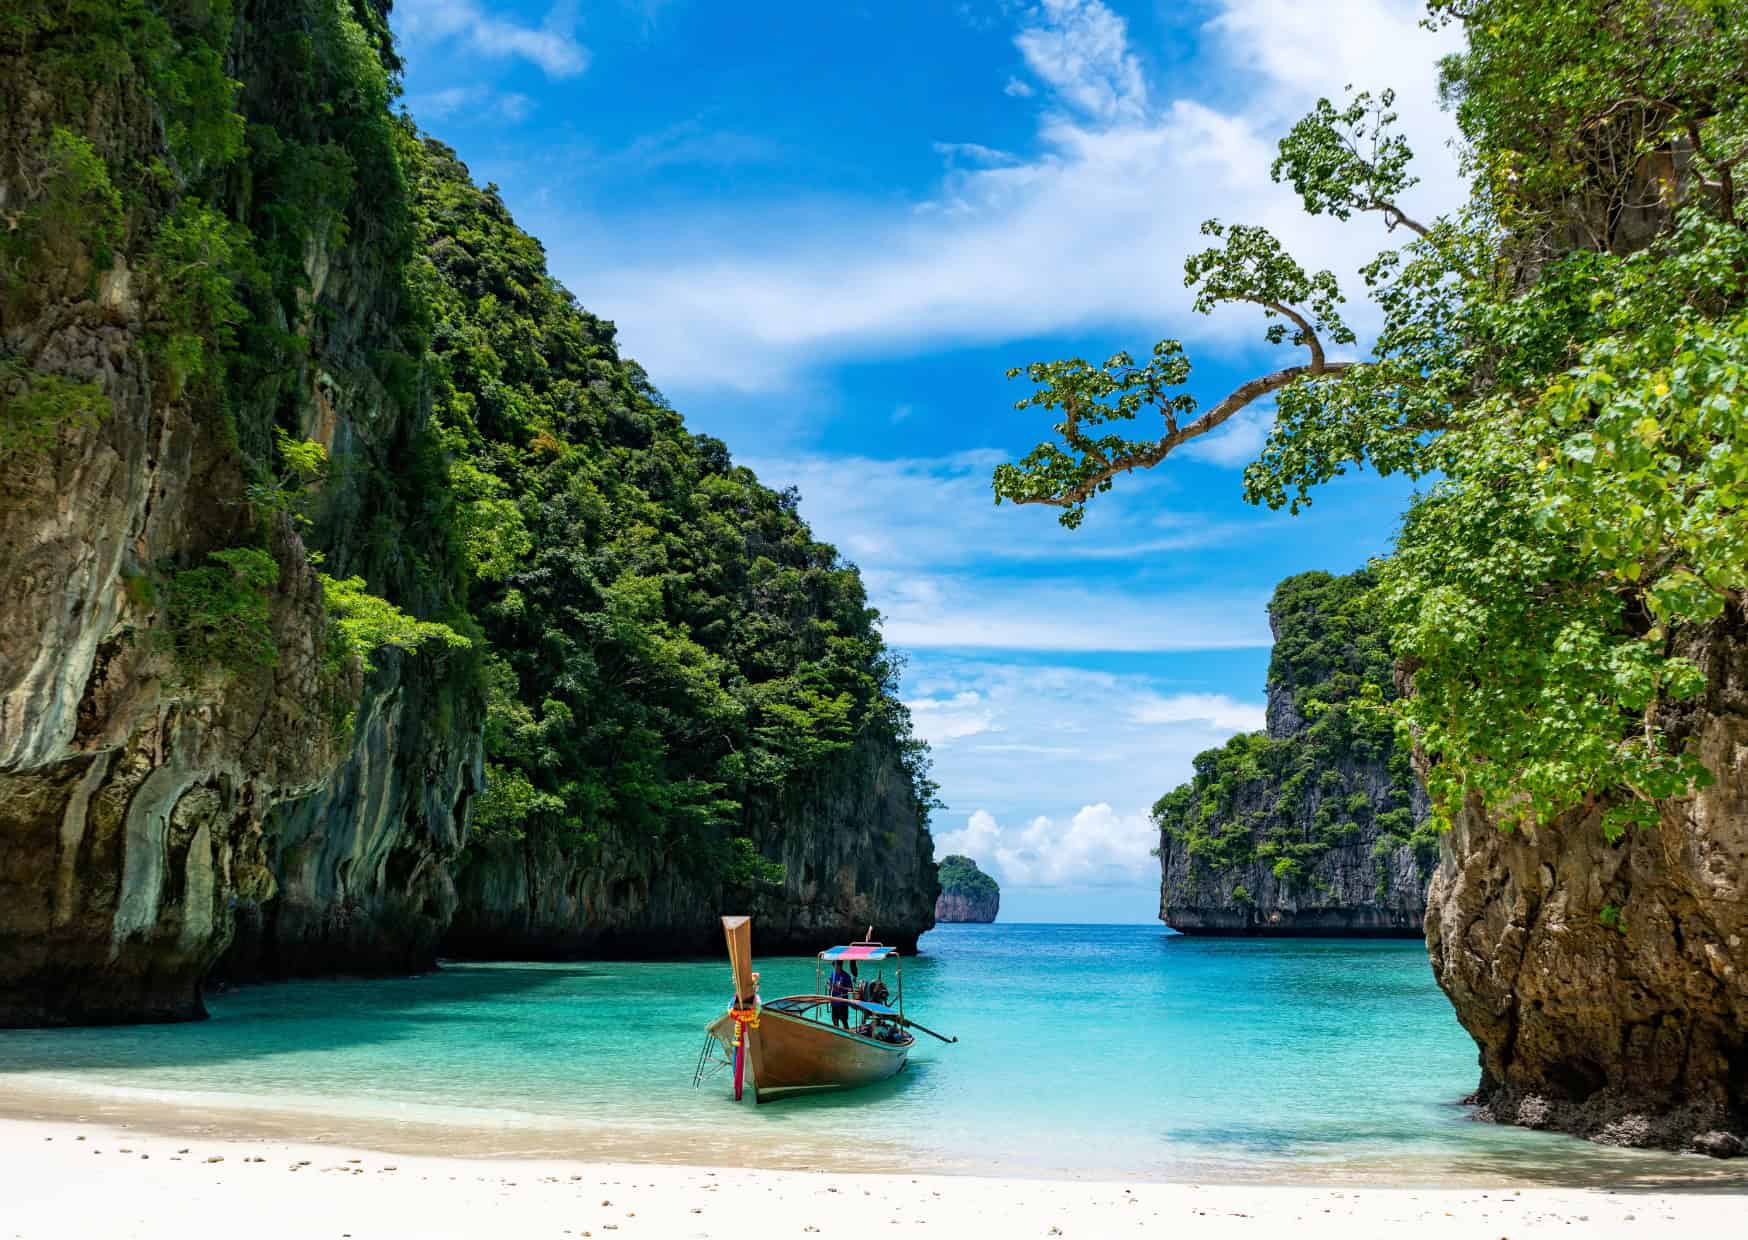
Why it’s tax‑friendly: Territorial system foreign income exempt if not remitted same year.
Perfect for: Retirees, digital nomads.
Residency options: Retirement visa, long‑term resident visa.
Hidden drawbacks: Complex rules on income remittance; vetting of Bangkok roads.
Why You Should Follow This Strategy
The strongest reason to consider a lower-tax country is simple: keeping more of your income can fundamentally change retirement or financial independence. A difference of several thousand dollars a year becomes significant over a decade. For retirees living primarily on pensions, investments, or savings, reducing unnecessary financial leakage can extend how long their money lasts.
Moving abroad can become even more powerful when tax savings are combined with lower everyday expenses. Cheaper housing, transportation, dining, and healthcare can amplify the benefit. Someone who struggles to maintain a comfortable lifestyle in an expensive American city may discover that the same income provides considerably more breathing room elsewhere.
It can also encourage Americans to examine their finances more carefully. Many people spend decades earning, saving, investing, and paying taxes without ever asking whether geography could change the equation. Researching international residency forces you to understand where your money goes, how different types of income are taxed, and which expenses actually matter most.
Another advantage is flexibility. You do not necessarily have to relocate forever. Some people test a destination for several months, obtain temporary residency, or spend a few years abroad before deciding whether the lifestyle truly suits them. Treating relocation as an experiment rather than a permanent escape can reduce the risk of making an expensive mistake.
Most importantly, the right international move can be about more than saving taxes. If a country also offers the climate, lifestyle, healthcare, culture, and pace of life you want, favorable tax treatment becomes an additional benefit rather than the entire reason for moving. That combination is where relocation becomes much more compelling.
Why You Should Not Follow This Strategy
You should not move abroad because of a viral headline promising dramatically lower taxes. International taxation is complicated, especially for Americans, and circumstances vary enormously depending on whether income comes from employment, pensions, investments, property, businesses, or retirement accounts. A tax strategy that works perfectly for one person may be disastrous for another.
Tax incentives can also change. Governments revise residency rules, eliminate special regimes, adjust qualifying requirements, and increase taxes when political priorities shift. Building your entire retirement plan around one favorable rule can leave you vulnerable if the program changes a few years later.
Another major mistake is ignoring exit costs and lifestyle expenses. International moves involve deposits, shipping, immigration fees, lawyers, tax professionals, property transactions, travel, and potentially maintaining financial ties in two countries. The first few years abroad can be considerably more expensive than an optimistic monthly budget suggests.
You should also consider what you may give up. Living thousands of miles from children, grandchildren, friends, or familiar healthcare providers has a cost that cannot easily be entered into a spreadsheet. Some people happily accept that tradeoff. Others eventually discover that cheap living and lower taxes do not compensate for feeling disconnected from home.
Finally, taxes should be one factor in relocation, not the entire decision. The best country financially can still be the wrong country personally. Before making a move, look at residency requirements, healthcare, language, housing, transportation, climate, bureaucracy, banking, estate planning, and how you actually spend your days. Saving money matters, but designing a life you want to live matters more.
The Controversial Truth
Here’s some hard wisdom: Tax havens are only worth it if you’re committed and compliant. Moving without a strategy invites risk: accidental dual taxation, lifestyle misalignment, or IRS audits. Plus, no‑tax destinations often swap income taxes for high VAT, property costs, or limited public services.
Some folks chase “no tax” like a jackpot but without substantial foreign income, it’s a vanity move. You’ll still pay U.S. taxes, file FBAR/8233, and navigate treaty benefits. Worse, flashy nations like Monaco come with outrageous living costs that offset any tax gain.
The real winners? Countries with territorial systems or targeted programs like Portugal, Panama, Costa Rica that reward your actual income structure while letting you live well. But do not assume a golden visa or fancy brochure equals a smarter move.
How to Choose the Right Country
Maximize income: UAE, Monaco, The Bahamas
Retire inexpensively: Portugal (NHR), Costa Rica
Stay extra‑fiscal: Panama, Malaysia, Thailand
Set up small business: Georgia, Bulgaria
Final Thoughts
Choosing a tax‑friendly country is more than tax arbitrage it’s a holistic lifestyle decision. You have to balance tax structure, residency rules, cost of living, quality of life, and U.S. tax obligations. No country is perfect but one may fit your goals better than any U.S. alternative.
Be honest about what matters. Are you chasing zero tax or a tax-smart, enjoyable life? If retirement income is your focus, countries like Portugal or Costa Rica offer smart niches. If you’re a high earner or business owner, UAE or Georgia might be better but research cost-of-living caveats carefully.
Finally, always consult cross-border financial and legal experts especially when U.S. tax and FATCA still apply. With the right plan, your move can be tax-efficient and enriching. Without it you may end up paying more in effort than you save in tax.

About the Author: Ruben, co-founder of Gamintraveler.com since 2014, is a seasoned traveler from Spain who has explored over 100 countries since 2009. Known for his extensive travel adventures across South America, Europe, the US, Australia, New Zealand, Asia, and Africa, Ruben combines his passion for adventurous yet sustainable living with his love for cycling, highlighted by his remarkable 5-month bicycle journey from Spain to Norway. He currently resides in Spain, where he continues sharing his travel experiences with his partner, Rachel, and their son, Han.