Most Americans dreaming of a European retirement have heard about Portugal’s tax breaks, and plenty know about Greece and its flat rate for foreign pensioners. Hardly anyone knows about Italy’s, and yet Italy’s may be the most generous deal of all.
Move to the right small town in southern Italy, and your entire foreign income, your pension, your Social Security, your investments, the lot, is taxed at a flat 7 percent. Not your Italian income only, everything you earn from abroad, at 7 percent, for up to a decade.
It is one of the best-kept secrets in European retirement, hiding in plain sight behind a single catch about where you have to live. Here is how the 7 percent deal works, the village rule at the heart of it, who actually qualifies, the perks that come bundled with it, and the honest caveats that mean you should never plan around it without professional help. None of this is tax advice, and the details are current for 2026.
The 7 Percent Deal
The core of the regime is beautifully simple, which is part of its appeal. Instead of paying Italy’s normal progressive income tax, which climbs from around 23 percent up past 43 percent, a qualifying foreign retiree pays a flat substitute tax of just 7 percent.
And it applies to all of your foreign-source income, not just your pension. Your pension, your Social Security, your dividends, your rental income from property back home, your investment gains abroad, all of it falls under the single 7 percent rate. For a retiree with a decent pension and some investments, the difference between 7 percent and Italy’s ordinary rates is enormous, potentially tens of thousands of euros a year.
Italy introduced this regime back in 2019, specifically to lure foreign pensioners into its emptying southern towns and villages. The idea was frankly to use tax to repopulate and revive the Mezzogiorno, the Italian south, by making it irresistibly cheap for retirees with foreign income to settle there. For the right person, it works spectacularly well.
It is worth pausing on just how generous that is by comparison. A retiree who might pay a third or more of their income in tax back home, or under Italy’s ordinary rates, can see that bill collapse to a flat seven cents on the euro. Over a decade, on a comfortable retirement income, the cumulative saving can run well into six figures, which is the kind of money that changes what a retirement looks like.
The Catch Is the Village
Of course, there is a catch, and it is a significant one: you cannot claim this deal living anywhere you like in Italy. You have to move to a qualifying small town in the south, and the rules about which towns qualify are specific.
The regime applies only to municipalities in eight southern Italian regions: Sicily, Sardinia, Calabria, Campania, Basilicata, Abruzzo, Molise, and Puglia. These are the regions of the Italian south, the Mezzogiorno, with their sun, their coastlines, their slower pace, and their lower costs, but also their distance from the big northern cities and their patchier infrastructure.
There is also a size limit on the town, and this is where a recent change matters. For years, the rule required a town of fewer than 20,000 inhabitants, which confined the deal to genuinely small places. As of April 2026, though, Italy raised that threshold to 30,000 inhabitants, which brought dozens of larger and more appealing towns into the scheme, places with more amenities and more life, widening the range of realistic options considerably. So the village rule is a little less restrictive than it used to be, though it still rules out the major cities entirely.
That trade-off is really the whole character of the deal. Italy is not handing this break to people who want to live in Rome or Milan; it is using it as a lure to draw retirees and their foreign money into the smaller towns of a region that has long struggled with depopulation and economic decline. You get a remarkable tax rate, and in return the Italian south gets new residents, new spending, and a little new life. Both sides are supposed to come out ahead.
Who Qualifies
Beyond the location, there are conditions you have to meet, and they are worth laying out clearly because missing one can void the whole thing. There are essentially four.
First, you must receive a pension from a foreign source. This is a regime built specifically for pensioners, so you need foreign pension income to get in the door; it is not open to people who simply have foreign investments but no pension. Second, you must not have been an Italian tax resident in the previous five years, which keeps it aimed at genuine new arrivals rather than people already living in Italy.
Third, you must actually transfer your tax residence to one of those qualifying southern towns, which in practice means genuinely moving there and spending enough of the year in Italy to count as resident. And fourth, you must be coming from a country that has a tax-cooperation agreement with Italy, which the United States does, so Americans clear that hurdle. Meet all four, and the 7 percent rate is yours to elect, for up to ten consecutive tax years.
The mechanics of claiming it matter, too, and are not something to improvise. You elect into the regime when you file, and the clock starts from the year your residence transfers, running for ten years and then stopping for good, with no renewal. Getting the residence transfer and the election right, in the correct order and with the correct documentation, is precisely the sort of thing that rewards good professional help and punishes a do-it-yourself approach.
More Than Just the 7 Percent
The low headline rate is not even the whole of the gift, because the regime comes bundled with some other significant perks that sweeten it considerably. For a retiree with assets spread across different countries, these can matter almost as much as the rate itself.
Under the scheme, you are exempt from Italy’s wealth taxes on foreign assets, the levies that would otherwise apply to foreign property and financial holdings. You are also freed from the usual obligation to report your foreign assets to the Italian authorities, a reporting burden that can be a real headache under the normal rules. In some respects the regime also eases the treatment of foreign wealth passing on at death.
Taken together, this makes the 7 percent regime not just a low rate but a genuinely light-touch tax life. Instead of navigating Italy’s famously complex tax system, with its wealth taxes and asset-reporting requirements, you pay one flat rate on your foreign income and are largely left alone about the rest. For retirees who value simplicity as much as savings, that streamlined quality is a large part of the appeal.
There is a real psychological comfort in it as well. Moving your financial life to a new country is daunting, and the prospect of wrestling with an unfamiliar and notoriously intricate tax system in a language you may not speak is enough to put many people off entirely. A regime that collapses all of that into one flat rate and a light reporting touch removes a large chunk of that fear, which is worth something beyond the pure arithmetic.
The Life You Would Be Buying
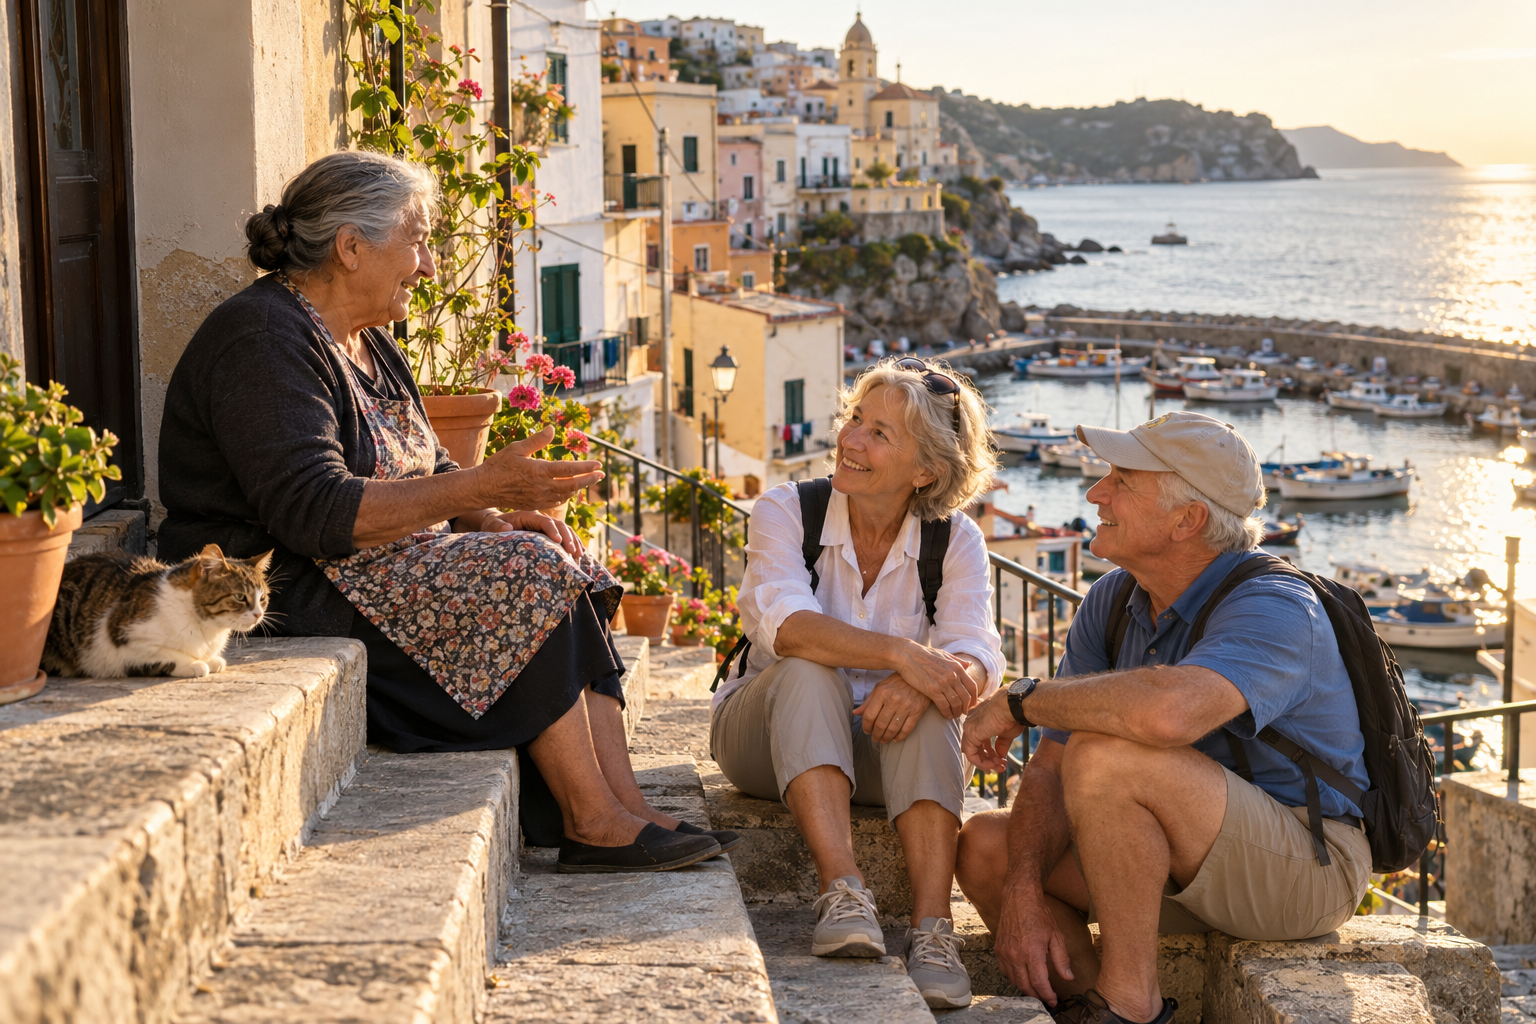
It is important to be honest that this is not free money; it is a trade, and the thing you are trading for the tax break is a particular way of life. To get the 7 percent, you have to genuinely live in a small town in the Italian south, and that reality deserves a clear-eyed look.
On the good side, the picture is genuinely lovely. Southern Italy offers sunshine, spectacular coastlines, extraordinary food, a deep and welcoming culture, and a cost of living far below that of northern Europe or the United States. In many of these towns your money stretches remarkably far, so the tax saving sits on top of an already affordable life, and the slower, more communal rhythm is exactly what many retirees are looking for.
On the other side, you must be realistic about what small-town southern Italian life involves. It can mean limited healthcare and amenities close by, patchier transport, a strong need to learn Italian, and real distance from the big-city comforts and the international connections some people cannot do without. The deal is extraordinary if you would genuinely love that life, and a poor bargain if you would merely tolerate it for the tax saving.
The lifestyle has to work on its own terms first. The happiest people in these towns are the ones who would have wanted to be there even without the tax break, and who treat the 7 percent as a wonderful bonus rather than the whole reason for the move.
The Honest Caveats
Here is where real caution is required, because retirement tax regimes are complex and getting them wrong is expensive. The 7 percent deal is remarkable, but it is not as simple as a single number, and several things need a professional’s eye before you lean on it.
For Americans in particular, there is a crucial wrinkle: the United States taxes its citizens on their worldwide income no matter where they live, so moving to Italy does not free you from the American tax system. You will still file US returns, and how your Italian 7 percent interacts with your US tax bill depends on the US-Italy tax treaty, the foreign tax credit, and the specific types of income you have. Some income, such as certain US government pensions, can be treated differently again. This interaction is genuinely complicated and is exactly where people get into trouble.
There are other caveats too. The regime lasts a maximum of ten years and then ends, after which normal Italian rates apply, so it is a long head start rather than a permanent escape.
The rules can also change, as the recent shift from 20,000 to 30,000 inhabitants shows. And the eligibility conditions are strict, with small mistakes in how you establish residence capable of disqualifying you entirely. For all these reasons, this is a decision to make with a cross-border tax professional who knows both the Italian regime and the US side, not off the back of an article.
Why Americans Have Not Heard of It
So why is this deal, arguably the most generous of Europe’s retirement tax regimes, so little known among Americans? Part of the answer is simply marketing, or the lack of it.
Portugal spent years actively courting foreign retirees and became famous for it, and Greece has promoted its own flat rate heavily. Italy’s regime, by contrast, is quieter and more hidden, partly because it is buried inside that off-putting requirement to live in a small southern town, which sounds, on first hearing, like a serious limitation rather than a feature. The deal does not fit neatly into a glossy relocation brochure, so it has stayed under the radar.
Yet for the right retiree, it may be the best deal going. If you would genuinely enjoy life in a sun-drenched town in Sicily, Puglia, or Calabria, with the food and the sea and the slower pace, then paying a flat 7 percent on all your foreign income for a decade is an almost unbelievable arrangement.
The honest bottom line is this: do not chase the tax break into a life you would not want, but if that life already appeals to you, Italy may be quietly offering one of the great retirement bargains in the world. Sit down with a qualified cross-border tax professional, run your actual numbers, and find out.

About the Author: Ruben, co-founder of Gamintraveler.com since 2014, is a seasoned traveler from Spain who has explored over 100 countries since 2009. Known for his extensive travel adventures across South America, Europe, the US, Australia, New Zealand, Asia, and Africa, Ruben combines his passion for adventurous yet sustainable living with his love for cycling, highlighted by his remarkable 5-month bicycle journey from Spain to Norway. He currently resides in Spain, where he continues sharing his travel experiences with his partner, Rachel, and their son, Han.