If you become a Spanish tax resident with money or property still sitting back in America, Spain wants to know all about it. Not to tax it, necessarily, but simply to see it: the country requires residents to file an annual inventory of their foreign assets, a form called the Modelo 720, and for years this one form had a reputation among expats that bordered on outright terror. The penalties for getting it wrong were so brutal that it became infamous among expats, a piece of paperwork people genuinely lost sleep over, and warned each other about in hushed tones on expat forums.
Then, in 2022, Europe’s highest court stepped in and struck those penalties down as illegal, and the whole picture changed almost overnight. The form that expat forums had treated as a trap suddenly became something much closer to ordinary paperwork. The obligation to file remains, but the nightmare attached to it is gone. What was once a genuine source of dread for law-abiding retirees is now, for most people, a manageable annual form. So here is what the Modelo 720 actually is, who has to file it and on what, why it used to be so frightening, the court ruling that defanged it, and how to handle it now without the panic it once caused. It is a rare case of a piece of bureaucracy that became genuinely less scary over the past few years, and it is worth knowing why.
What follows is what the form is, the fifty-thousand-euro rule and its three categories, why the old version terrified people, the 2022 ruling that changed everything, and how to approach it calmly today.
What the Modelo 720 Is
At its core the Modelo 720 is an informational declaration, filed with the Spanish tax authority, in which a Spanish resident reports the assets they hold outside Spain. It is not a tax and it collects no money; like the American FBAR that it strongly resembles, it is purely a disclosure, a way for the Spanish government to know what wealth its residents are holding abroad. You are not paying anything by filing it; you are simply telling the authorities what you own beyond Spain’s borders. The tax, if any is due on that foreign wealth, comes through your ordinary income and wealth tax returns; the 720 itself is just the inventory.
The obligation falls on Spanish tax residents, the people who live in Spain and are taxed there on their worldwide income, which for an American who has genuinely moved to Spain means you. Non-residents do not file it, and neither do people who spend only part of the year in Spain without becoming resident. But once you are a Spanish resident with meaningful assets back home, American bank accounts, an investment portfolio, a house you kept in the States, the Modelo 720 becomes part of your annual compliance, sitting alongside your Spanish income tax return as one of the things a resident with foreign wealth simply has to deal with. For the typical American retiree who kept their US accounts and perhaps a house, this means the 720 almost certainly applies, since a normal retirement portfolio comfortably clears the threshold in at least one category. It is worth understanding early, because it catches people who never imagined that moving to Spain would require them to hand the Spanish government a list of their American holdings, and yet that is exactly what it does. The assumption that your American assets are purely an American matter does not survive contact with Spanish residency.
The Fifty-Thousand Rule and the Three Categories
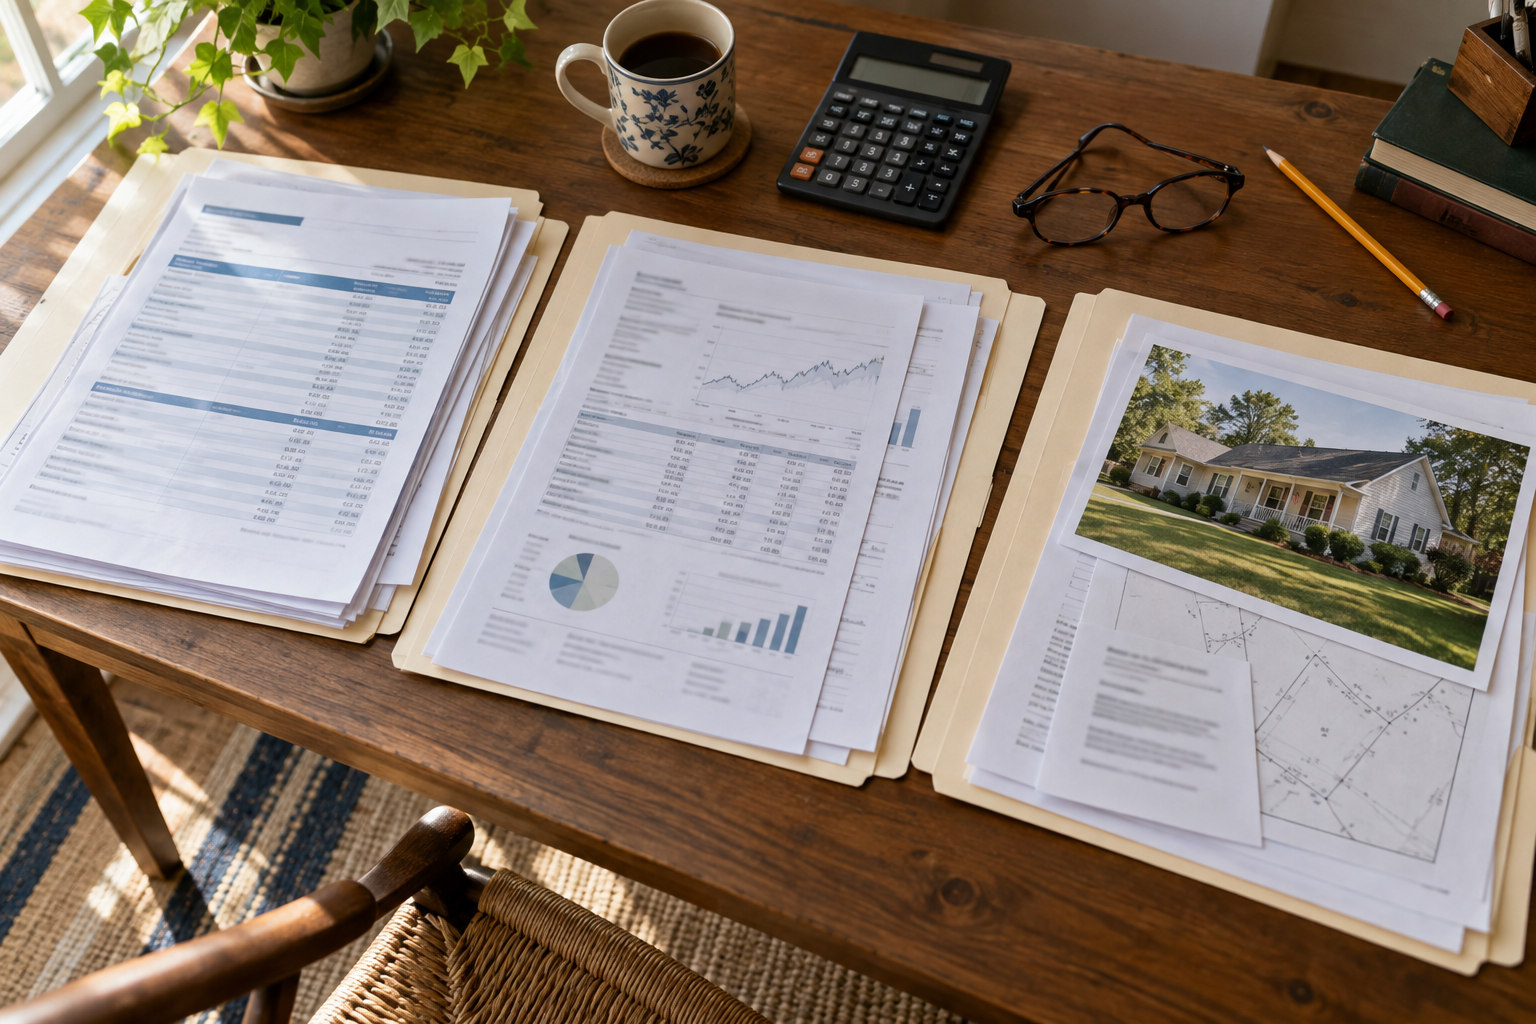
The mechanics of who actually has to file come down to a threshold and three separate baskets, and getting the structure right matters. Your foreign assets are divided into three categories: first, bank accounts held outside Spain; second, investments, securities, pensions, and insurance held abroad; and third, real estate located outside Spain. The rule is that you must file if any one category exceeds fifty thousand euros. Crucially, the threshold is assessed per category, not across your total foreign wealth, so the categories do not add together.
This has a genuinely useful consequence that people often miss. Because each category is measured separately against the fifty-thousand-euro line, you could hold, say, forty thousand euros in foreign bank accounts and forty thousand euros in a foreign property, eighty thousand in total, and still not have to file, because neither individual category crossed the threshold. It is only when a single category exceeds fifty thousand that the obligation kicks in for that category. This is genuinely worth understanding rather than guessing at, because people either panic that they must file when they need not, or assume they are exempt when a single account has quietly crossed the line.
The deadline is the end of March, covering the assets you held as of the previous December. And there is a helpful rule about repeat filing: once you have filed, you generally do not need to file again in later years unless something changes meaningfully, specifically if a declared category rises by more than twenty thousand euros, if you acquire new assets in a category you had not declared, or if you sell or close something you previously reported. So for many people, the Modelo 720 is a one-time effort followed by years of nothing, rather than an annual chore, provided their foreign holdings stay roughly stable. You do the work once, in your first year of residency, and then largely forget about it unless your finances shift substantially.
How It Differs From the American FBAR
For an American who has moved to Spain, there is a particular wrinkle worth spelling out, which is that you may now owe two separate foreign-asset disclosures to two different governments, and they do not work the same way. Back in the United States you likely already know the FBAR, the American report of foreign accounts. Now, as a Spanish resident, you also owe the Modelo 720. Both are informational disclosures rather than taxes, and both exist so a government can see the wealth its residents hold abroad, but the resemblance ends there, and confusing one for the other is a good way to get into trouble.
The differences are concrete. The American FBAR triggers at a combined ten thousand dollars across all your foreign accounts, a very low bar that almost any expat crosses, while the Spanish Modelo 720 uses a much higher fifty thousand euros, assessed separately in each of three categories. The FBAR covers financial accounts; the Modelo 720 also reaches real estate, which the FBAR does not, so the American house you kept back home shows up on the Spanish form even though it never appears on the American one.
They go to different agencies, on different deadlines, in different currencies, and with different definitions of what counts. The upshot for the American in Spain is that both reports may be required in the same year, describing overlapping but not identical sets of assets, and each must be done on its own terms. This is not as onerous as it sounds once you have a system, but it is a genuine doubling of the paperwork, and it is worth realizing from the outset that satisfying one does absolutely nothing to satisfy the other. Being a diligent FBAR filer for years back home earns you no credit at all with the Spanish authorities, who have never heard of it and want their own form. Many expats in exactly this position simply hand both to a cross-border accountant and let them keep the two straight.
Why It Used to Be Terrifying
To understand why this form has such a fearsome reputation, you have to look at what the penalties used to be, because they were, by any measure, draconian. When the Modelo 720 was introduced in 2012, the regime attached to it was extraordinarily harsh. Failing to declare an asset, or declaring it late or incorrectly, could trigger fines of five thousand euros per piece of missing information, with steep minimums, so a few oversights could rapidly run into tens of thousands of euros in penalties for a form that raised no tax at all.
Worse still was the treatment of undeclared assets themselves. Under the old rules, if you failed to declare a foreign asset, Spain could treat its entire value as unjustified income, taxed at the top rate, and they could do so with effectively no statute of limitations, reaching back indefinitely, and then pile a penalty of a hundred and fifty percent penalty on top. The practical effect was that a modest failure to report could theoretically cost you more than the asset itself was worth, an outcome so disproportionate that it terrified law-abiding expats who were merely confused by an unfamiliar form. This was the source of the Modelo 720’s dark reputation: not the filing itself, which is straightforward, but the sense that a small honest mistake could be financially catastrophic. Stories circulated of retirees facing fines larger than the savings they had forgotten to mention, and whether or not every story was accurate, the fear they spread was very real. For a decade, that fear hung over every resident with foreign assets, and it was not irrational, because the penalties really were that severe on paper.
The 2022 Ruling That Changed Everything
The turning point came in January 2022, when the Court of Justice of the European Union, Europe’s highest court, ruled that Spain’s penalty regime for the Modelo 720 was disproportionate and contrary to European Union law. It was a landmark decision, and it forced Spain to dismantle the very features that had made the form so frightening. The court’s reasoning was straightforward: a penalty regime can enforce disclosure, but it cannot be so wildly out of proportion to the offense that it effectively confiscates people’s assets, and Spain’s old rules had crossed that line. In response, Spain reformed the rules within months, stripping out the draconian penalties and replacing them with the ordinary, proportionate penalty regime that applies to Spanish tax matters generally.
The change is dramatic in its effect. The old five-thousand-euros-per-item fines are gone, replaced by far more modest amounts. Most importantly, the single most punitive feature, the treatment of undeclared assets as unjustified income taxed at the top rate with no time limit and a hundred-and-fifty-percent penalty, has been eliminated entirely.
What remains is a genuine but manageable obligation: you still must file if you cross the thresholds, and there can still be penalties for getting it wrong or filing late, but they are now reasonable rather than ruinous, and voluntary late filing is treated far more leniently than it once was. A late or imperfect filing today might cost a modest sum rather than threatening your financial survival, which is the whole difference between a chore and a catastrophe. The result is that the Modelo 720 has been transformed from one of the most feared pieces of paperwork in the expat world into what it always should have been: a routine informational filing with sensible consequences for error. The obligation survived the court ruling; the terror did not.
How to Approach It Calmly Today
So how should a Spanish resident with foreign assets think about the Modelo 720 now, on the other side of the court ruling? Calmly, and as a manageable annual housekeeping item rather than a source of dread. The essential steps are simple. If you are a Spanish tax resident and your foreign holdings exceed fifty thousand euros in any of the three categories, file the form by the end of March, listing the relevant assets. Gather your year-end statements for each account, investment, and property, note the values as of the last day of December, and enter them; the tax authority is looking for a complete and honest picture, not perfection to the last cent. If nothing much changes from year to year, you will not need to file again, so it is often a one-time task.
It is informational, so filing it does not cost you any tax; you are simply disclosing, not paying. Nothing leaves your bank account as a result of filing the 720 itself, which is worth repeating because the form’s fearsome old reputation leaves many people bracing for a bill that never comes.
A few practical notes round out the picture. The penalties, while now proportionate, are not zero, so it is still worth filing correctly and on time rather than ignoring the obligation, and if you have fallen behind, the far gentler post-reform regime makes catching up much less painful than it would have been a few years ago. Someone who discovered an old missed filing today faces a modest fix, where a few years back the same oversight could have been financially devastating. Cryptocurrency held abroad is reported not on the 720 but on a separate newer form, so crypto holders have their own parallel obligation to be aware of.
And because the form intersects with the rest of your Spanish and American tax picture in ways that can get complicated for anyone with substantial or complex assets, this is an area where a good cross-border tax adviser earns their fee, particularly in your first year of residency when you are getting everything set up. But the headline is a reassuring one. The Modelo 720 is a real obligation that a resident with foreign wealth genuinely has to meet, but it is no longer the financial minefield it was, and approached in good time and in good faith, it is simply a form, not a threat. The right attitude is neither the old dread nor careless neglect, but the calm diligence you would give any other piece of annual paperwork that matters.

About the Author: Ruben, co-founder of Gamintraveler.com since 2014, is a seasoned traveler from Spain who has explored over 100 countries since 2009. Known for his extensive travel adventures across South America, Europe, the US, Australia, New Zealand, Asia, and Africa, Ruben combines his passion for adventurous yet sustainable living with his love for cycling, highlighted by his remarkable 5-month bicycle journey from Spain to Norway. He currently resides in Spain, where he continues sharing his travel experiences with his partner, Rachel, and their son, Han.